
Disclaimer:
This material may contain third-party opinions, none of the data and information on this webpage constitutes investment advice
The content shared in economics articles is solely for research and informational purposes.
We are not a financial advisory service, and the information provided should not be considered investment or trading advice.
The Forces Shaping Markets: AI Investment, Bank Mergers, Chips and Interest Rates
Key Points
AI investment is making a substantial contribution to U.S. economic growth, while questions remain about how much strength outside the AI sector is being masked by the boom.
U.S. banking mergers are accelerating, with 81 deals announced in the first half of 2026, the highest first-half total since 2021.
Japan and the United States have agreed on a semiconductor manufacturing project worth up to about $21 billion in New York, strengthening cooperation around chip supply chains and economic security.
Bank of England Chief Economist Huw Pill said a potential interest-rate increase should not necessarily be interpreted as the beginning of a long series of rate hikes.
Together, the developments highlight several forces influencing financial markets: technology investment, corporate consolidation, semiconductor spending, inflation and monetary policy.
advertisement
Markets Face a Convergence of AI, Banking and Interest-Rate Forces
Financial markets are being shaped by several powerful and closely watched developments on October 15, 2026, ranging from the continuing artificial intelligence investment boom in the United States to renewed banking consolidation, a major Japan-U.S. semiconductor investment project, and changing expectations for interest rates in the United Kingdom.
The developments come from different parts of the global economy, but they share a common theme: companies, governments and investors are adjusting to the enormous capital requirements created by new technology, changing financial conditions and efforts to strengthen economic security. The result is a market environment in which AI spending, bank consolidation, semiconductor production and monetary policy are all important factors.
AI Investment Is Supporting U.S. Growth
The continuing AI buildout is making a significant contribution to the U.S. economy. A Reuters analysis published on October 15, 2026, said most estimates indicate that roughly one-third of U.S. economic growth over the past couple of years has been associated with the AI buildout. Reuters also reported that nearly one-quarter of U.S. imports in 2025 were AI-related goods, while AI-related stocks, depending on how they are defined, represented about half of the market capitalization of the S&P 500.
That concentration gives the technology investment cycle an unusually important role in the broader market. Large investments in data centers, technology equipment and related infrastructure have supported economic activity and helped sustain investor interest in companies connected with artificial intelligence.
But the Reuters analysis raises an important question: whether the AI boom is adding strength across the wider economy or partly concealing weakness elsewhere. That distinction matters because a slowdown in AI investment could have consequences beyond technology companies if other areas of the economy remain soft.
U.S. Investment Picture Is More Complicated Than the AI Boom Suggests
Research discussed by Reuters from New York Federal Reserve economist Julian di Giovanni suggests that the increase in AI-related imports has not produced the large deterioration in the U.S. trade and current-account deficits that might otherwise be expected.
The current-account balance can be understood in terms of a country's gross savings and gross domestic investment. Reuters reported that the U.S. current-account gap widened through early 2025 but subsequently narrowed during a period of tariffs introduced by the Donald Trump administration.
The analysis also points to an important feature of the investment data. While investment in information technology, equipment and software has increased, declines in other categories have offset part of that increase. These areas include factory construction, residential investment and spending on structures and equipment outside data centers and technology equipment.
Reuters reported that aggregate investment as a share of U.S. GDP has remained broadly stable at just under 22% for about eight years. Gross domestic investment averaged 21.3% of GDP during the five years before the pandemic and 21.5% during the three years after the launch of ChatGPT, according to the analysis.
This suggests that the AI investment surge should not automatically be interpreted as a broad increase in total investment across the entire economy. Instead, part of the change reflects a shift in where investment is taking place.
Financial Risks Could Increase If AI Spending Slows
The AI boom also raises questions for investors because so much market and economic attention is now tied to the technology cycle.
Reuters' analysis noted that household saving has declined somewhat in recent years, partly reflecting wealth effects associated with higher equity values. Business saving has fallen only slightly, while government "dis-saving"—reflecting wider government budget deficits—has moved in the opposite direction from private saving.
Reuters reported that government dis-saving accounted for 1.75 percentage points of the 2.4 percentage-point increase in the U.S. current-account deficit since the pandemic, while falling private savings contributed about half a percentage point and business investment contributed little.
The analysis cautions that the situation could change if spending increasingly becomes financed through debt or equity. A sudden slowdown in AI investment, a financing shock or a major stock-market sell-off could therefore have broader economic consequences.
These are risks identified in the Reuters commentary, not predictions that such an event will occur. The distinction is important for investors assessing whether the current AI-led market strength can continue.
U.S. Banks Accelerate Merger Activity
At the same time, the U.S. banking industry is undergoing another period of consolidation. Global Finance reported that 81 banking deals were announced in the United States during the first half of 2026, the largest first-half total since 2021.
The renewed merger activity has been supported by a combination of a more favorable regulatory environment, excess capital at some large banks and the rising expense of competing in artificial intelligence and technology.
Regulatory changes began in May 2025, when the Office of the Comptroller of the Currency restored expedited review and a streamlined application process for bank mergers. Two months later, the Federal Deposit Insurance Corp. rescinded its 2024 bank-merger policy statement and returned to earlier guidelines, according to Global Finance.
The changes have coincided with shorter deal-completion times. Global Finance, citing S&P Global Market Intelligence, reported that the median period from announcement to completion declined from 187 days in 2024 to 134 days in 2025 and 94 days so far in 2026.
Bank Consolidation Is Also About Technology Costs
The motivation for bank mergers extends beyond traditional economies of scale. Banks face increasing costs associated with developing and maintaining technology and AI capabilities, making scale and technological capacity more important competitive considerations.
Global Finance reported that research by Bain & Co. found 17 U.S. lenders held more than $10 billion in excess capital at the end of June, with seven holding more than $20 billion. The same research found that deals combining scale with new capabilities produced total shareholder returns 14 to 18 percentage points higher than scale-only transactions over the previous two years.
The trend is visible in several large transactions. Santander's $12.2 billion acquisition of Webster Financial created a bank with $327 billion in assets, while Fifth Third's $10.9 billion purchase of Comerica produced the ninth-largest U.S. bank, according to Global Finance. The merger of Pinnacle Financial Partners and Synovus created another institution with more than $120 billion in assets.
The market for bank acquisitions also shows a gap between what buyers and potential sellers consider acceptable valuations. Global Finance reported that the median price paid for a bank seller was about 141% of tangible book value, while 68% of banks surveyed by Bank Director said they would require at least 175% to sell.
Japan and U.S. Expand Semiconductor Investment
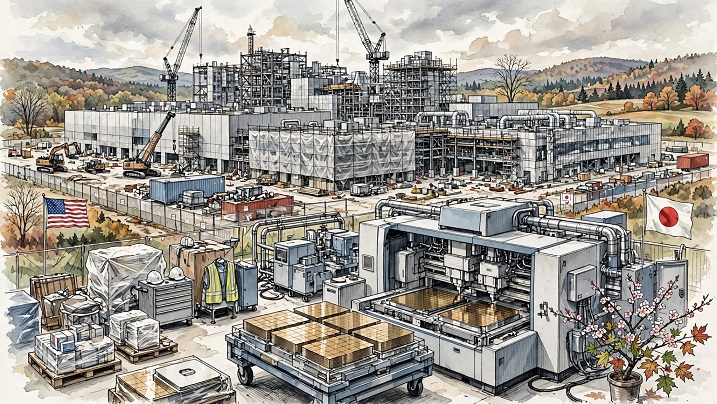
Another major development is emerging in the semiconductor industry. Japan and the United States have agreed on a semiconductor production project worth up to roughly $21 billion in New York, according to the Kyodo News report supplied for this article.
The project involves GlobalFoundries Inc., which announced plans to build two new chipmaking facilities in Malta, in upstate New York. Japan's Ministry of Economy, Trade and Industry confirmed that GlobalFoundries is the main company involved and said the first facility would cost about $10 billion.
About $10 billion is expected to be invested during the first phase, while GlobalFoundries expects the first new factory to begin production in 2029, according to the Kyodo report.
The project is the third initiative to be launched under a bilateral trade agreement reached by Japan and the United States last year in exchange for tariff relief from the United States.
Chip Supply Chains Become Part of Economic Security
The semiconductor project is intended to increase the resilience of the Japan-U.S. chip supply chain by expanding production of mature-node semiconductors. These chips remain important across a broad range of industries, including automobiles, industrial machinery, smartphones and AI data centers, according to Kyodo.
The project also illustrates how semiconductor production has become closely connected with national economic-security strategies. Governments and companies are seeking greater resilience in chip supply chains while demand for computing infrastructure continues to grow.
Japan's Ministry of Economy, Trade and Industry said the project could also create opportunities for Japanese companies supplying equipment and materials. Tokyo Electron Ltd. and Screen Holdings Co. have expressed interest in supplying chipmaking equipment, while Tokyo Ohka Kogyo Co. is interested in supplying materials and components. Renesas Electronics Corp. is interested in purchasing the chips, according to the Kyodo report.
Japanese Trade Minister Ryosei Akazawa said the strategic investment initiative would now include semiconductor manufacturing alongside an earlier project involving power supply for an AI data center and other facilities.
U.S. President Donald Trump said the semiconductor project would create 27,000 construction and supply-chain jobs and more than 1,000 additional highly skilled manufacturing jobs in New York. Those figures are Trump's stated estimates as reported by Kyodo and should therefore be distinguished from independently verified employment totals.
Bank of England Rate Outlook Adds a Monetary Policy Dimension
While technology and corporate investment are driving activity in some areas, interest-rate expectations remain another major influence on markets.
Bank of England Chief Economist Huw Pill said on October 15, 2026, that a future interest-rate increase should not automatically be interpreted by investors as the beginning of a prolonged series of rate hikes. His comments came as markets were expecting a quarter-point increase following the Bank of England's next meeting.
Pill said investors should not assume that a move now would place the central bank on the same path as the series of increases seen in 2022 and 2023. He characterized the current inflation shock as different from that earlier period.
Pill has voted for higher rates since April, and he had pushed back on Wednesday against financial-market expectations for four rate increases over the following 12 months, according to The Business Times.
Inflation Remains a Concern for the Bank of England
The central bank's caution reflects continuing concerns about inflation dynamics in the United Kingdom.
Pill warned about what he described as "insidious" catch-up dynamics, in which workers seek higher wages to compensate for previous increases in prices. He said that dealing with those pressures could require a more prolonged period of restrictive monetary policy.
He also said that higher bond yields in advanced economies probably reflected, at least partly, an increase in the real neutral interest rate needed to stabilize inflation. That was another factor pointing toward the possibility of higher rates, according to The Business Times.
The comments do not amount to a commitment to a particular sequence of future rate decisions. Instead, they indicate that policymakers are weighing inflation risks while trying to avoid giving investors the impression that one increase necessarily signals a long tightening cycle.
What These Developments Mean for Financial Markets
Taken together, the four developments show why financial markets cannot be understood through a single indicator or sector.
The AI investment cycle is supporting U.S. growth and has become highly significant for the value of major publicly traded companies. At the same time, the Reuters analysis raises questions about the strength of other parts of the economy and the potential consequences of a slowdown in AI-related spending.
The U.S. banking sector is responding to regulatory changes, excess capital and rising technology costs through greater consolidation. The pace of deal completion has accelerated, while large transactions are changing the scale of major financial institutions.
The Japan-U.S. semiconductor agreement demonstrates the growing importance of chip manufacturing to economic security and the AI infrastructure economy. Meanwhile, Bank of England policy expectations show that inflation and interest rates remain central to the investment environment.
For investors, the developments underline several areas to monitor: the sustainability of AI capital spending, the pace and valuation of bank mergers, the execution of new semiconductor investments and the direction of interest-rate policy. None of these developments guarantees a particular market outcome, but each can influence corporate investment, financing conditions and investor sentiment.
Key Points Summary
AI investment remains a major contributor to U.S. economic growth.
AI-related stocks account for about half of S&P 500 market capitalization, depending on the definition used by the Reuters analysis.
81 U.S. banking deals were announced in the first half of 2026.
Japan and the United States agreed on a semiconductor project worth up to approximately $21 billion in New York.
Bank of England Chief Economist Huw Pill said a future rate hike should not necessarily signal a prolonged series of increases.
What This Means
Today's developments show that markets are being influenced by a combination of technology investment, corporate consolidation, strategic manufacturing and monetary policy.
For investors and businesses, the key issues to watch are whether AI investment remains strong, how quickly U.S. bank consolidation continues, whether the Japan-U.S. semiconductor project progresses as planned, and how the Bank of England responds to persistent inflation pressures.
The sources do not establish that these developments will produce a particular direction for global stock markets. Instead, they identify several important forces that could influence financial conditions and corporate decisions.
advertisement
Frequently Asked Questions
Why is AI important to the U.S. economy?
AI-related investment in infrastructure, technology equipment and software has become a significant contributor to U.S. economic activity. Reuters cited estimates that roughly one-third of U.S. economic growth over the past couple of years was associated with the AI buildout.
Are U.S. banks merging more frequently?
Yes. Global Finance reported that 81 banking deals were announced in the United States during the first half of 2026, the highest first-half total since 2021.
Why are U.S. banks pursuing mergers?
According to Global Finance, the consolidation is being encouraged by a more favorable regulatory environment, excess capital at larger lenders and the rising cost of developing technology and AI capabilities.
How large is the Japan-U.S. semiconductor project?
Japan and the United States agreed on a semiconductor manufacturing project worth up to approximately $21 billion in New York. The first phase is expected to involve about $10 billion in investment, according to Kyodo News.
When is the first new semiconductor factory expected to begin production?
According to the Kyodo News report supplied for this article, GlobalFoundries expects the first new facility to begin production in 2029.
What did the Bank of England's chief economist say about rate hikes?
Huw Pill said that a future rate increase should not necessarily be viewed as the beginning of a long series of increases. He also expressed concern about inflation and wage-price dynamics in the United Kingdom.
Does a Bank of England rate increase guarantee more increases?
No. Pill specifically cautioned investors against assuming that an increase would automatically begin a prolonged sequence of rate hikes.
Sources
Reuters — AI investment boom may be papering over US economic cracks
Kyodo News — Japan, U.S. launch $21 bil. chip project to boost economic security — October 15, 2026.
No additional sources were used for the article's factual claims.
Disclaimer:
This material may contain third-party opinions, none of the data and information on this webpage constitutes investment advice
The content shared in economics articles is solely for research and informational purposes.
We are not a financial advisory service, and the information provided should not be considered investment or trading advice.
Thank you !