
Global Stock Market Outlook: Election Shifts, Earnings and Growth Stocks Shape Investor Focus
Key Points
Global markets reacted to the latest U.S. midterm election results as investors assessed the potential implications for technology regulation, government policy and corporate earnings.
MercadoLibre continued to report strong growth across e-commerce and digital financial services, although increased investment and shipping incentives are putting pressure on profitability.
Rocket Lab's business momentum remains significant, with revenue and backlog growth, but its share price has experienced a substantial decline from its record closing price.
Goldman Sachs lowered its Booking Holdings price target, citing demand-related headwinds, even as the travel company reported growth in room nights and gross bookings.
Corporate earnings, management forecasts and expectations for artificial intelligence infrastructure remain important factors influencing investor sentiment.
advertisement
Global Markets React to U.S. Midterm Election Results
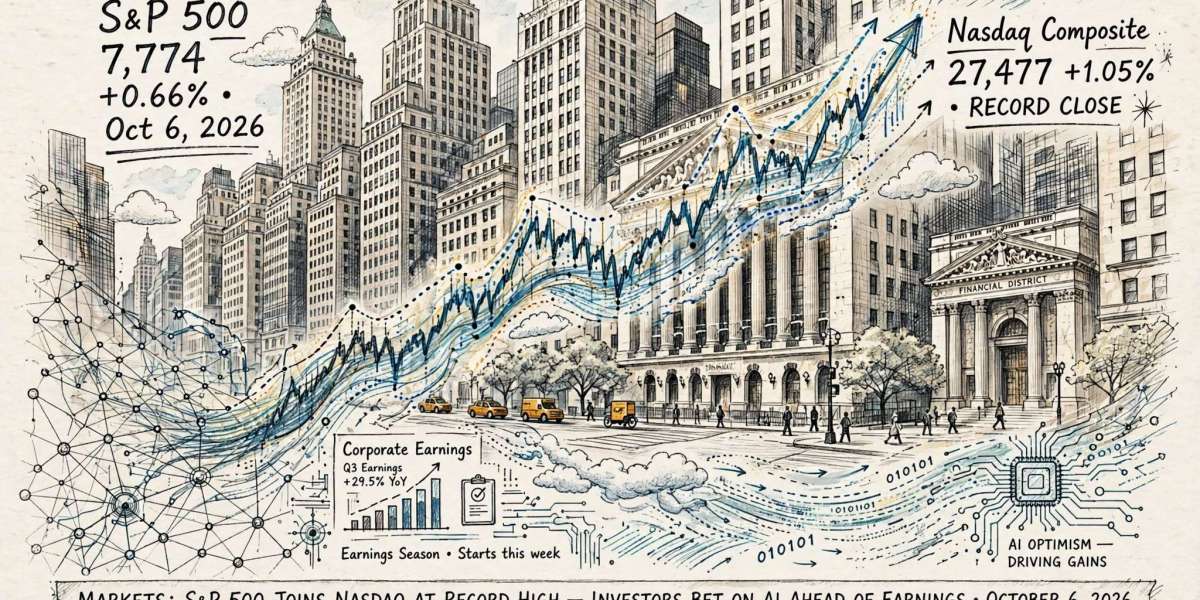
Global financial markets experienced a changing trading environment on Wednesday, November 4, as investors assessed the results of the U.S. midterm elections and considered their potential implications for economic policy, technology regulation and corporate earnings.
According to Reuters reporting published through Euronext, Democrats won control of both the Senate and the House of Representatives. The political result initially unsettled markets, with investors considering whether the outcome could increase the likelihood of regulatory pressure on major technology companies, particularly those involved in artificial intelligence.
U.S. stock futures had fallen by as much as 2% overnight before recovering and moving back into positive territory. The broader market picture was more mixed, with the MSCI All-World index rising 0.13% and Europe's STOXX 600 gaining approximately 0.5%.
The Russell 2000 futures also advanced around 0.7%, indicating that smaller U.S. companies were participating in the recovery.
Technology shares faced pressure in early trading. Reuters reported declines among major companies, including Tesla and other large technology stocks. These movements reflected investor uncertainty rather than confirmation of any specific future regulatory action.
The election result could influence discussions around technology policy, taxation, government spending and oversight. However, the immediate market reaction should not be interpreted as evidence that any particular policy change is guaranteed.
For investors, the key question is how the political outcome may affect corporate earnings, business investment and the regulatory environment over the coming months.
Treasury Yields and Currency Markets Reflect Changing Sentiment
Bond and currency markets also responded to the election developments.
Reuters reported that U.S. Treasury prices advanced as investors moved toward government bonds during the initial period of uncertainty. The yield on the 10-year U.S. Treasury note was reported at approximately 4.92%, after briefly falling to 4.89% overnight.
Currency movements were also notable. The euro traded around $1.133, while the British pound reached approximately $1.348. Both currencies strengthened against the U.S. dollar during the reported session.
The Swiss franc and Japanese yen also gained, reflecting demand for currencies often associated with defensive positioning during periods of market uncertainty.
Meanwhile, Brent crude oil traded around $103.17 per barrel, down approximately 0.4%.
These movements illustrate how political developments can influence several financial markets simultaneously. Equities, bonds, currencies and commodities may react differently depending on how investors interpret the potential consequences for economic growth, inflation and government policy.
Nevertheless, a single trading session does not establish a lasting market trend. Investors will continue watching economic indicators, central-bank expectations and corporate results to determine whether the latest movements develop into a broader shift in sentiment.
MercadoLibre: Strong Growth Continues Despite Profitability Pressure
MercadoLibre remains one of the companies attracting attention among growth-oriented investors, particularly because of its expanding e-commerce and digital financial services operations across Latin America.
In its second-quarter 2026 results, the company reported revenue growth of 50% year over year, marking its fastest growth rate in almost four years, according to the supplied Motley Fool report.
Gross merchandise volume increased 44% year over year, reflecting continued expansion in the company's online marketplace. Its financial services business also delivered strong activity, with total payment volume rising 56% and assets under management increasing 68%.
The company's customer base continued to expand. Unique active buyers increased 26%, while monthly active users grew 30%. Items purchased per buyer also advanced 14%, suggesting that existing customers were becoming more active on the platform.
Another important operating indicator was delivery performance. The source reported that 78% of shipments, excluding orders for which customers selected slower shipping, were delivered within 48 hours.
MercadoLibre operates across 18 countries, giving it exposure to markets where e-commerce and digital financial services still have room to develop. Its combination of online retail, payments and financial products provides several potential sources of future growth.
However, strong revenue and transaction growth do not automatically translate into higher profits.
The company has faced profitability pressure over the past two quarters as it continues investing in its operations. In Brazil, its largest market, MercadoLibre lowered the threshold for free shipping from R$79 to R$19. The move was intended to strengthen its competitive position and encourage more purchases, but it also increased shipping-related costs.
This illustrates the balance the company must maintain between gaining market share and protecting operating margins.
The Motley Fool article presents MercadoLibre as an attractive long-term investment opportunity. That assessment is an investment opinion, not a guaranteed outcome. Investors should consider the company's growth potential alongside its valuation, competitive environment, spending requirements and ability to convert expanding activity into sustainable profitability.
Rocket Lab: A Sharp Share-Price Decline Meets Stronger Business Activity
Rocket Lab has experienced substantial share-price volatility, demonstrating how rapidly investor expectations can change in the space industry.
According to the supplied Motley Fool article syndicated through The Globe and Mail, Rocket Lab shares reached a record closing price of $150.23 on May 27. At the time covered by the article, the shares were trading near $52, approximately 65% below that record.
The company's earlier trading history provides useful context. Rocket Lab previously reached a closing high of $20.72 on September 9, 2021, before falling 83% to $3.53 on April 15, 2024.
The shares later recovered, closing at $22.41 on November 21, 2024, above the previous 2021 record. This historical sequence is important because it shows that the stock has experienced major declines and recoveries before. It does not, however, establish that another recovery will necessarily follow.
The company's operating performance has continued to develop. Rocket Lab finished 2024 with 16 launches and annual revenue of $436 million, representing growth of 78% from the previous year. It also reported a net loss of $190 million for 2024.
In the second quarter of 2026, revenue increased 62% year over year to $234 million. Its backlog reached a record $2.36 billion, an increase of 137%, according to the supplied article.
Rocket Lab also completed 20 launches by November 2, 2026, exceeding its total for all of 2024. The company had previously secured an $816 million Space Development Agency contract in 2025, adding to its government-related business opportunities.
Its second-quarter 2026 GAAP net loss narrowed to $49 million, compared with $66 million in the same quarter of 2025. Although the improvement is encouraging, the company remained loss-making under this measure.
There are still important execution risks. The first flight of its Neutron rocket was delayed to 2027, according to the supplied article. Delays in major development programs can affect expectations, spending and the timing of future commercial opportunities.
The article also describes a proposed $8 billion acquisition of Iridium, including debt, which Rocket Lab is expected to complete in mid-2027. In this transaction, Rocket Lab is the acquiring company, not the company being acquired.
Despite its expanding business activity, Rocket Lab's share-price decline highlights the difference between operational progress and stock-market valuation. A company can increase revenue and backlog while its shares fall if investors reconsider how much they are willing to pay for future growth.
Booking Holdings: Goldman Sachs Lowers Its Price Target
Booking Holdings faced additional analyst scrutiny after Goldman Sachs reduced its price target for the online travel company.
According to the supplied Investing.com report, Goldman Sachs lowered its target from $180 to $175 while maintaining a Neutral rating.
The adjustment followed Booking Holdings' third-quarter 2026 financial results and reflected concerns about demand conditions. Analyst Eric Sheridan identified softer international demand, tensions in the Middle East and elevated air prices as potential headwinds for the travel sector.
The company's reported results presented a mixed picture.
Booking Holdings recorded earnings per share of $4.66, exceeding the consensus estimate of $4.49. However, revenue reached $8.9 billion, below the expected $9.54 billion.
Room nights increased 7% year over year, compared with 5% growth in the previous quarter. Gross bookings advanced 10%, or approximately 11% when adjusted for foreign-exchange movements.
The company has also been using artificial intelligence to improve operational efficiency, including customer support and engineering productivity. Management has discussed the potential for AI-related improvements to support productivity and margins as technology costs evolve.
The supplied report also highlights Booking Holdings' long-term framework of approximately 8% annual growth in bookings, 8% revenue growth and 15% earnings-per-share growth.
These figures represent management's framework and expectations, not guaranteed future results.
Goldman Sachs' decision to maintain a Neutral rating suggests that the analyst sees a balance between the company's opportunities and the risks facing its business. For investors, the main issues include travel demand, international market conditions, pricing, operating efficiency and the company's ability to convert bookings growth into revenue and earnings.
Pershing Square: Bill Ackman Highlights AI Infrastructure and a Potential Housing-Finance Opportunity
Artificial intelligence infrastructure and the future of U.S. housing finance were also important themes in the supplied coverage of Pershing Square Holdings' third-quarter 2026 earnings call.
According to the supplied GuruFocus report, Bill Ackman and Pershing Square Chief Investment Officer Ryan Israel argued that markets may be underestimating the earnings potential of major cloud-computing and hyperscale technology companies.
The discussion focused on the continuing demand for computing capacity and the potential financial benefits for companies operating large cloud infrastructure businesses.
The report highlighted expectations for strong cloud growth at major technology companies, including Amazon and Microsoft. These expectations reflect management and investor assessments of future demand for AI-related infrastructure. They should not be treated as confirmed future revenue results.
Ackman also discussed a potential opportunity involving Fannie Mae and Freddie Mac, the two major U.S. housing-finance enterprises.
The supplied report described his view that the market may be mispricing the potential value of the companies and referred to an estimated opportunity of approximately $500 billion.
That figure represents Ackman's assessment, rather than an established valuation or a guaranteed gain. Any potential outcome would depend on political decisions, regulatory developments, the companies' financial positions and the eventual structure of any changes to their status.
The discussion illustrates how investors are evaluating opportunities beyond the immediate performance of publicly traded technology companies. AI infrastructure and housing finance represent very different sectors, but both are attracting attention because of their potential long-term economic significance.
Huntsman: Earnings Show Improvement, but Losses Remain
Huntsman Corporation's third-quarter results provide another example of the challenges facing companies in the chemicals and materials industry.
The supplied Simply Wall St report described a decline in the company's share price following its latest earnings announcement, despite improvements in several operating measures.
Huntsman reported third-quarter revenue of approximately $1.717 billion, compared with $1.460 billion in the same period a year earlier.
Its basic earnings per share reflected a loss of $0.09, narrower than the $0.14 loss reported a year earlier. The company also reported a trailing 12-month net loss of approximately $107 million, compared with $254 million in the prior period referenced by the source.
The report highlighted third-quarter free cash flow of approximately $82 million and an improvement in EBITDA of more than $100 million compared with 2025.
It also pointed to positive EBITDA in the European Polyurethanes business and a 12% increase in Advanced Materials volumes.
These developments suggest improvement in parts of the company's operations. However, they do not mean that Huntsman has returned to overall profitability.
The supplied report also discussed the proposed merger with Olin, which was expected to close in early 2027. The companies have identified more than $400 million in annual cost and integration synergies as a target.
Those projected synergies should be understood as an objective, not savings that have already been achieved. The eventual outcome will depend on the transaction's completion, integration execution, market conditions and the ability to realize the expected efficiencies.
For investors, Huntsman's results highlight the importance of looking beyond revenue growth. Profitability, cash generation, debt, demand conditions and the execution of restructuring or merger plans remain important considerations.
What Investors May Watch Next
The latest developments show that the market is responding to several different forces rather than following one clear direction.
Political uncertainty is influencing expectations around technology regulation and government policy. At the same time, investors are assessing corporate earnings, analyst forecasts and the sustainability of growth in sectors ranging from online commerce to space technology and cloud computing.
Several factors may remain particularly important:
1. The implications of the U.S. election: Investors will watch for clearer indications of how the new political balance could affect regulation, taxation, government spending and technology policy.
2. AI infrastructure spending: Demand for computing capacity and cloud services remains a major investment theme. However, investors will need to distinguish actual reported growth from forecasts and expectations.
3. Corporate profitability: MercadoLibre and Huntsman demonstrate why revenue growth alone is not enough. Shipping costs, operating expenses, restructuring and investment decisions can influence margins and earnings.
4. Valuation and execution risks: Rocket Lab's share-price decline illustrates how a high-growth company can face significant valuation adjustments even while its business expands. Investors will also monitor the Neutron development schedule and the proposed Iridium acquisition.
5. Consumer and travel demand: Booking Holdings' results highlight the importance of international travel conditions, air prices and consumer spending.
Ultimately, the direction of global equities will depend on how these factors translate into actual financial performance. Strong growth can support a company's long-term prospects, but valuation, profitability and execution remain essential parts of any investment assessment.
Key Points Summary
Global markets responded to the U.S. midterm election results, with initial pressure on stock futures followed by a recovery.
Treasury, currency and commodity movements reflected changing investor sentiment.
MercadoLibre reported strong second-quarter growth in revenue, e-commerce activity and financial services, while higher investment costs continued to pressure profitability.
Rocket Lab's revenue and backlog increased, but its shares remained far below their record closing price.
Goldman Sachs reduced its Booking Holdings price target to $175 and maintained a Neutral rating.
Pershing Square's comments highlighted expectations surrounding AI infrastructure and a potential housing-finance opportunity.
Huntsman reported higher revenue and several operating improvements, although it remained loss-making.
Investors are likely to focus on earnings quality, valuations, demand conditions and the execution of corporate strategies.
What This Means for Investors
The latest market developments reinforce the importance of separating business performance from stock-market performance.
A company may report rapid revenue growth, expanding customers or a larger order backlog without necessarily delivering immediate share-price gains. Investors also consider valuation, profitability, competition, capital requirements and the possibility that expectations have already been reflected in a stock's price.
MercadoLibre's results show the opportunities available to businesses expanding digital commerce and financial services in Latin America, while its shipping investments demonstrate the cost of pursuing market share.
Rocket Lab's experience highlights the volatility associated with high-growth companies and the risks of relying on historical recoveries as a guide to future performance.
Booking Holdings and Huntsman demonstrate why investors should examine both revenue and profitability, while Pershing Square's commentary shows how expectations around AI and financial restructuring can influence investment discussions.
For long-term investors, the central task remains evaluating whether a company's future cash flows and business prospects justify its current valuation.
advertisement
Frequently Asked Questions [FAQ]
1. Why did global stock markets react to the U.S. midterm elections?
Investors considered how the election results could affect technology regulation, government policy, taxation and corporate investment. Initial concerns pushed U.S. stock futures lower before they recovered.
2. Why is MercadoLibre attracting investor attention?
The company reported 50% year-over-year revenue growth in the second quarter of 2026, alongside strong increases in gross merchandise volume, payment volume and active users. However, higher operating and shipping investments remain important profitability considerations.
3. Why have Rocket Lab shares fallen so sharply?
The supplied Motley Fool report describes a decline from a record closing price of $150.23 on May 27 to approximately $52 at the time of writing. Share-price movements reflect changing investor expectations and valuation, even as the company reports revenue and backlog growth.
4. Is Rocket Lab acquiring Iridium or the other way around?
The supplied Motley Fool article syndicated through The Globe and Mail describes Rocket Lab as the company that agreed to acquire Iridium in a transaction valued at approximately $8 billion, including debt. It does not describe Iridium as acquiring Rocket Lab.
5. Why did Goldman Sachs lower its Booking Holdings price target?
The supplied Investing.com report says Goldman Sachs reduced its target from $180 to $175 while maintaining a Neutral rating. The analyst cited demand-related headwinds, including softer international demand, Middle East tensions and elevated air prices.
6. What is the significance of Pershing Square's comments about AI companies?
The supplied GuruFocus earnings-call coverage describes Bill Ackman and Ryan Israel as arguing that markets may underestimate the earnings potential of major cloud and hyperscale companies. These are investment views and expectations, not guaranteed financial outcomes.
7. Has Huntsman returned to profitability?
The supplied Simply Wall St report describes improvements in revenue, free cash flow and certain operating measures. However, it also reports a loss in basic earnings per share and a trailing 12-month net loss. The improvements should not be interpreted as a confirmed return to overall profitability.
8. What should investors focus on in the current market environment?
Investors may want to monitor corporate earnings, valuations, interest rates, consumer demand, technology investment, geopolitical developments and companies' ability to turn revenue growth into sustainable profits.
Sources
1. The Motley Fool – MercadoLibre
https://www.fool.com/investing/2026/11/04/down-38-is-mercadolibre-stock-a-better-buy-than-sp/
2. Investing.com – Goldman Sachs Lowers Booking Holdings Stock Price Target
3. Reuters, published through Euronext – Stocks Rally, Dollar Dips After Democrats' Midterm Sweep
https://live.euronext.com/en/financial-news/stocks-rally-dollar-dips-after-democrats-midterm-sweep
4. The Motley Fool article by Daniel Sparks, syndicated through The Globe and Mail – Rocket Lab Stock Has Crashed Even Harder Before. Here's How Long the Last Comeback Took
5. GuruFocus – Pershing Square Holdings Ltd. Q3 2026 Earnings Call Highlights
6. Simply Wall St – Huntsman (HUN) Stock Falls After Q3 Earnings Extend Losses
Additional Verified Sources:
None. No additional sources have been used.
Disclaimer:
This material may contain third-party opinions, none of the data and information on this webpage constitutes investment advice
The content shared in economics articles is solely for research and informational purposes.
We are not a financial advisory service, and the information provided should not be considered investment or trading advice.
Market quotations and forecasts are attributed to the supplied reports; figures that differ between reports have not been silently reconciled.
Thank you !